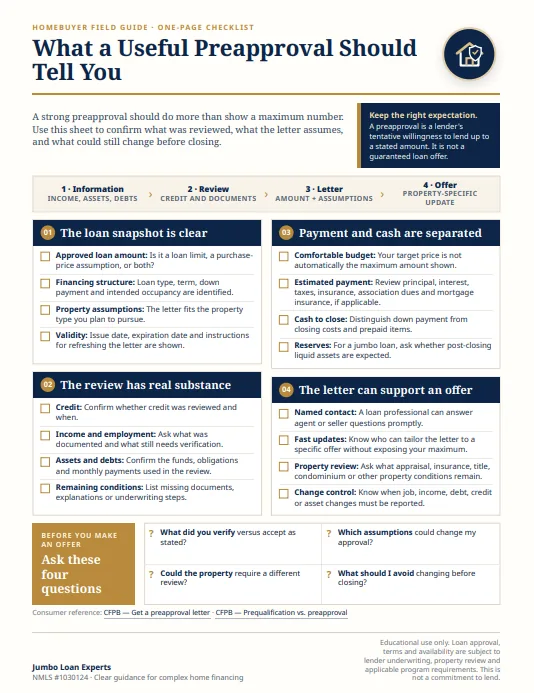
A strong preapproval should do more than show a maximum number. Use this guide to confirm what was reviewed, what the letter assumes, and what could still change before closing.
Keep the right expectation
A preapproval is a lender's tentative willingness to lend up to a stated amount. It is not a guaranteed loan offer.
A useful preapproval moves through four stages: information (income, assets and debts), review (credit and documents), the letter (amount and assumptions), and the offer (a property-specific update).
The loan snapshot is clear
- Approved loan amount: Is it a loan limit, a purchase-price assumption, or both?
- Financing structure: Loan type, term, down payment and intended occupancy are identified.
- Property assumptions: The letter fits the property type you plan to pursue.
- Validity: Issue date, expiration date and instructions for refreshing the letter are shown.
The review has real substance
- Credit: Confirm whether credit was reviewed and when.
- Income and employment: Ask what was documented and what still needs verification.
- Assets and debts: Confirm the funds, obligations and monthly payments used in the review.
- Remaining conditions: List missing documents, explanations or underwriting steps.
Payment and cash are separated
- Comfortable budget: Your target price is not automatically the maximum amount shown.
- Estimated payment: Review principal, interest, taxes, insurance, association dues and mortgage insurance, if applicable.
- Cash to close: Distinguish down payment from closing costs and prepaid items.
- Reserves: For a jumbo loan, ask whether post-closing liquid assets are expected.
The letter can support an offer
- Named contact: A loan professional can answer agent or seller questions promptly.
- Fast updates: Know who can tailor the letter to a specific offer without exposing your maximum.
- Property review: Ask what appraisal, insurance, title, condominium or other property conditions remain.
- Change control: Know when job, income, debt, credit or asset changes must be reported.
Before you make an offer, ask these four questions
- 1.What did you verify versus accept as stated?
- 2.Which assumptions could change my approval?
- 3.Could the property require a different review?
- 4.What should I avoid changing before closing?