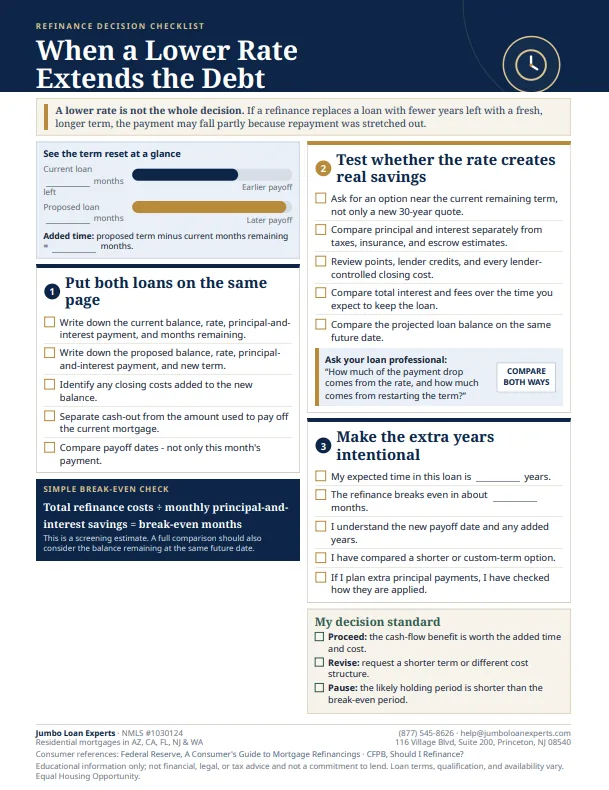
A lower rate is not the whole decision. If a refinance replaces a loan with fewer years left with a fresh, longer term, the payment may fall partly because repayment was stretched out.
See the term reset at a glance
Write down how many months are left on your current loan (the earlier payoff) and how many months the proposed loan runs (the later payoff).
Added time = proposed term - current months remaining
Put both loans on the same page
- Write down the current balance, rate, principal-and-interest payment, and months remaining.
- Write down the proposed balance, rate, principal-and-interest payment, and new term.
- Identify any closing costs added to the new balance.
- Separate cash-out from the amount used to pay off the current mortgage.
- Compare payoff dates, not only this month's payment.
Simple break-even check: total refinance costs ÷ monthly principal-and-interest savings = break-even months
This is a screening estimate. A full comparison should also consider the balance remaining at the same future date.
Test whether the rate creates real savings
- Ask for an option near the current remaining term, not only a new 30-year quote.
- Compare principal and interest separately from taxes, insurance, and escrow estimates.
- Review points, lender credits, and every lender-controlled closing cost.
- Compare total interest and fees over the time you expect to keep the loan.
- Compare the projected loan balance on the same future date.
Ask your loan professional
"How much of the payment drop comes from the rate, and how much comes from restarting the term?"
Make the extra years intentional
- I know my expected time in this loan, in years.
- I know roughly how many months it takes the refinance to break even.
- I understand the new payoff date and any added years.
- I have compared a shorter or custom-term option.
- If I plan extra principal payments, I have checked how they are applied.
My decision standard
- Proceed: The cash-flow benefit is worth the added time and cost.
- Revise: Request a shorter term or different cost structure.
- Pause: The likely holding period is shorter than the break-even period.