Use one standardized figure to see beyond the headline rate, first payment, and cash due at closing.
Calculate the five-year borrowing cost in three moves
- 1.Find total paid: On page 3 of each Loan Estimate, find the first amount under "In 5 years."
- 2.Find principal paid: Find the second five-year amount: the portion scheduled to reduce your balance.
- 3.Subtract: Total paid minus principal paid gives the five-year interest-and-fee cost shown on the form.
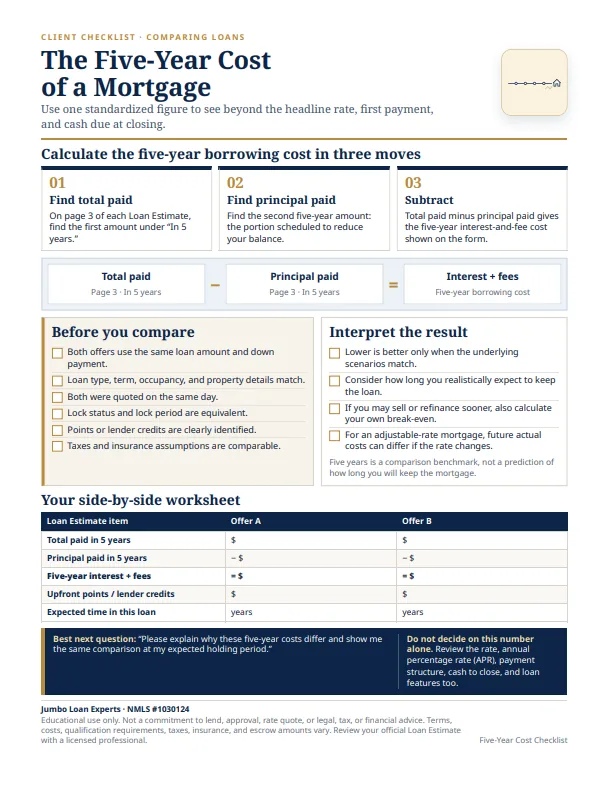
Total paid (page 3, In 5 years) - principal paid (page 3, In 5 years) = five-year borrowing cost
Before you compare
- Both offers use the same loan amount and down payment.
- Loan type, term, occupancy, and property details match.
- Both were quoted on the same day.
- Lock status and lock period are equivalent.
- Points or lender credits are clearly identified.
- Taxes and insurance assumptions are comparable.
Interpret the result
- Lower is better only when the underlying scenarios match.
- Consider how long you realistically expect to keep the loan.
- If you may sell or refinance sooner, also calculate your own break-even.
- For an adjustable-rate mortgage, future actual costs can differ if the rate changes.
Five years is a comparison benchmark, not a prediction of how long you will keep the mortgage.
Your side-by-side worksheet
For Offer A and Offer B, write down:
- Total paid in 5 years
- Principal paid in 5 years
- Five-year interest and fees
- Upfront points or lender credits
- Expected time in this loan, in years
Best next question
"Please explain why these five-year costs differ and show me the same comparison at my expected holding period."
Do not decide on this number alone. Review the rate, annual percentage rate (APR), payment structure, cash to close, and loan features too.